01
Start with the questions
We begin with the people, debts, income and business activities that could be affected. Yvonne will explain which providers and products can be considered, along with any limits relevant to the conversation.
Insurance conversations · Aotearoa New Zealand
I'm Yvonne. I help families and business owners understand questions around life, medical, income protection and business insurance. Conversations are available in English and 中文.
001 / Decision check
Ask what is in scope, what is not, and which written information supports the recommendation.
Before acting on personal advice
How I work
A useful insurance conversation should make the questions, scope and written records clearer.
01
We begin with the people, debts, income and business activities that could be affected. Yvonne will explain which providers and products can be considered, along with any limits relevant to the conversation.
02
Conversations can be in English or 中文. The insurer's original application and policy wording remain the documents to rely on, so important explanations should also be kept in writing.
03
A review can help you note what has changed, what is still unclear and which questions should be answered in writing before you make a decision.
Personal insurance
Four personal and business cover topics. What is relevant depends on your dependants, debts, income, existing policies and business responsibilities.
01
Explore what financial gap may remain for the people who depend on you if you die or become seriously ill.
02
Understand how private medical cover may interact with surgery, specialist care and diagnostics.
03
Examine how a policy may respond if illness or injury prevents you from working, and what evidence or offsets may apply.
04
Identify the people and financial obligations a business depends on, then check which risks a policy may or may not address.
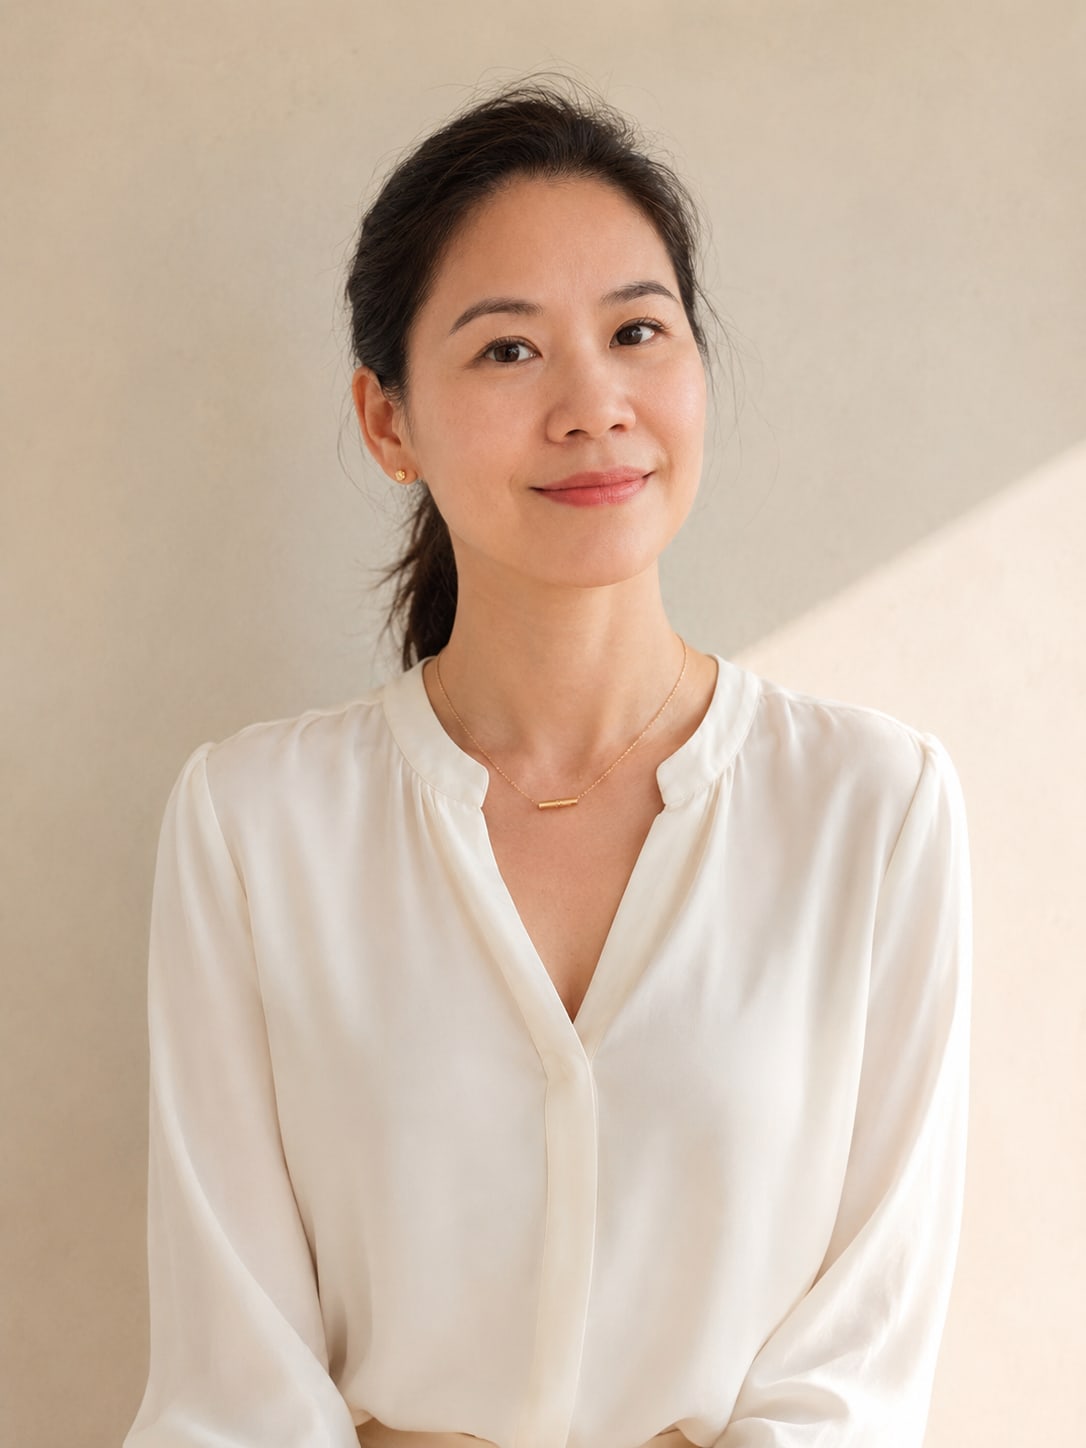
Yvonne Chen · Senior Insurance Adviser
About Yvonne
iCare Insurance is built around plain-language conversations for families, new migrants and small business owners who want to understand the documents and questions involved before making an insurance decision.
The starting point is a conversation about your situation, budget and the trade-offs you are comfortable making. Yvonne will explain which providers and products can be considered, any relevant limitations and how the service is paid for.
Conversations are available in English and 中文. Important explanations should still be checked against the insurer's original documents and kept in writing.
Review scenarios
These are illustrative review scenarios, not testimonials, client records or promises of a particular outcome.
You have cover through a bank, employer or another arrangement, but you are not sure what would be paid, when it would end or whether it still matches your debts and dependants.
Review scenario · a family with dependants
What to check Bring the policy schedule and latest renewal notice. Record the benefit, owner, expiry or renewal terms, exclusions and unanswered questions before considering any change.
Your income varies and the terms 'waiting period', 'benefit period' and 'eligible income' do not clearly show what evidence might be needed if you cannot work.
Review scenario · a self-employed person
What to check Prepare recent accounts, tax records and existing cover. Ask how disability, income, offsets and claim evidence are defined in the actual policy wording.
You can discuss insurance more comfortably in Chinese, while the insurer's application, policy definitions and exclusions are written in English.
Review scenario · a bilingual household
What to check Ask for key explanations in writing, check the insurer's original wording and use a qualified interpreter where a medical or legal conversation requires one.
Frequently asked
Fees, commissions and other incentives can depend on the service, provider and product. Before you decide whether to proceed, ask for the current written disclosure that applies to the advice, including who may pay iCare, any amount you may need to pay, how it is calculated and how conflicts are managed.
What to check in an adviser disclosureACC generally responds to covered personal injuries and has its own eligibility rules; it is not ordinary illness insurance. Private life, trauma and income-protection policies use different definitions, exclusions and claim tests. Check the relevant ACC guidance and the actual policy wording rather than assuming one automatically fills every gap in the other.
Compare ACC and income protectionDo not cancel or replace existing cover based on a website summary. Start by checking the policy owner, benefit, expiry or renewal terms, exclusions and whether any new underwriting would apply. A review can also end with no change; any personal recommendation should explain the differences in writing.
Annual insurance policy review checklistYes. Yvonne can discuss insurance in English and 中文 (普通话). The insurer's original application and policy documents remain the documents to rely on. Ask for important explanations in writing and consider a qualified interpreter where a medical or legal conversation requires one.
Medical insurance for Chinese-speaking familiesStart a conversation
Request a conversation in English or 中文. Confirm the available format, timing, scope and any applicable fee before the meeting.